Rates Just Hit 4.60%. Who’s Checking Whether You’re Overpaying?
- October 1, 2026
Another rate rise.
Another notification from the bank.
Another quiet recalculation of the monthly budget at the kitchen table.
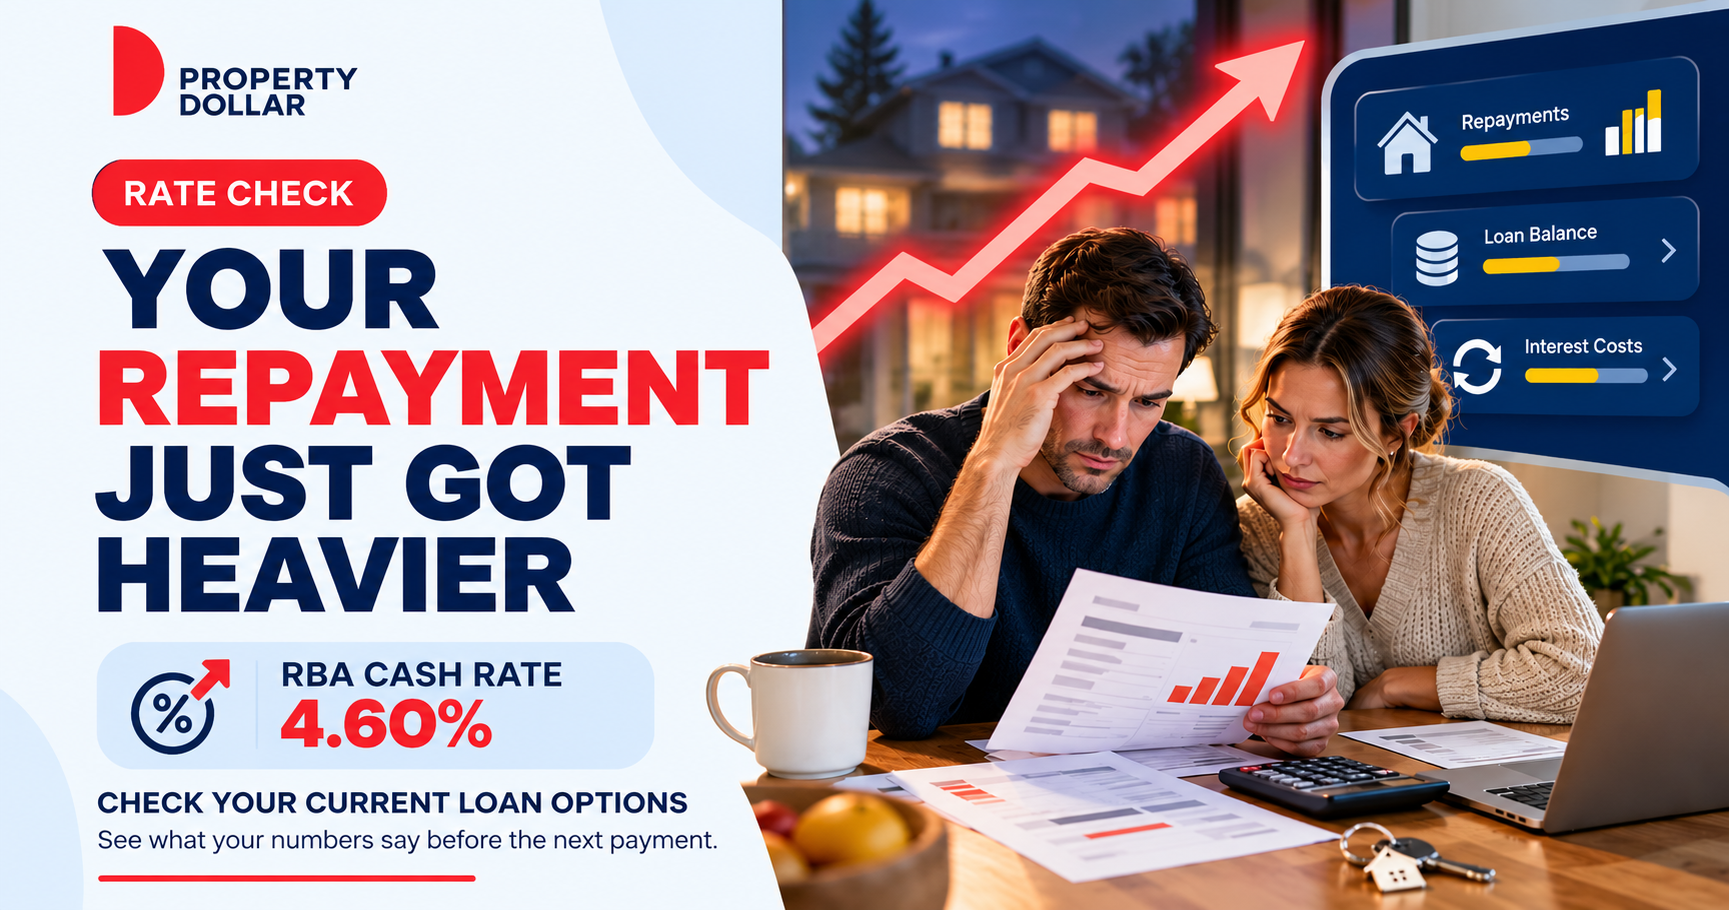
If that sounds familiar, you are not imagining the squeeze. On 29 September the Reserve Bank lifted the cash rate 25 basis points to 4.60%, the fourth hike this year and, according to ABC News, the highest since November 2011. The big four, CBA, NAB, Westpac and ANZ, will pass on the full increase from 9 October, with Macquarie following on 15 October. So the real question is not whether your repayment goes up. It is whether anyone is helping you work out what to do next.
$91 a month. Again.
ABC News estimates that a 0.25 point rise adds about $91 a month to a $600,000 variable loan with 25 years to run. Stack up all four rises this year and the same borrower is paying roughly $360 more every month, about $4,320 a year. Your number will differ with your balance, term and rate, but the direction is the same for almost every variable borrower.
If you want to see how rate changes can affect the cash flow of an investment property, read our guide to stress testing your investment property cash flow when interest rates change.
NAB’s advice to customers worried about their finances was to contact the bank early.
That is sensible. But notice who is expected to make the first move: you. Which raises an awkward follow up. When did you last check that your loan is still competitive, or even that you know exactly what you owe?
The squeeze nobody texts you about
Repayments are the loud half of the problem. The quiet half is your equity.
Cotality’s September index, published 1 October, showed national home values down 1.1% in the month and 5.2% below their March peak. Sydney is 8.6% off its February peak and Melbourne 7.2% off its November 2025 peak. Cotality’s Tim Lawless says 97% of capital city suburbs fell over the last three months, and he considers a 10% to 15% peak to trough decline a reasonable estimate. Those are forecasts rather than certainties, but they explain why lenders and borrowers are both watching LVR more closely.
Property value: $800,000
Loan balance: $600,000
Starting LVR: 75%
If the property value falls 10%: LVR is about 83%
If the property value falls 15%: LVR is about 88%
You have not missed a payment or changed a thing, yet your position has shifted toward the thresholds lenders use when they price loans and assess refinances. This example is illustrative and ignores principal already repaid.
For a deeper look at this relationship, read Property Values Are Falling: What Happens to Your Equity and LVR?
A lender may also assess your property differently from the value you see elsewhere. We explain why in Two Buyers, Same Suburb, Different Valuations.
APRA’s June quarter data, as reported by Canstar, shows how thin the buffer is for recent buyers: 4.31% of new owner occupier loans had a deposit of 5% or less.
Higher repayments on one side, shrinking equity on the other. And the only way most people find out where they really stand is a phone call to the bank or a spreadsheet they last updated in March.
Forget the spreadsheet. Let your loan report to you.
This is the gap Property Dollar was built to close. Instead of asking you to remember to check, our system periodically checks your loan against market data and lets you know when you are off the pace, so a rate that has drifted or a structure that no longer suits you does not sit unnoticed for years. You stay updated without having to go looking.
Your LVR and equity are calculated automatically from your mortgage details and property values, so after a rate rise or a price move you can see your position without waiting for a bank to answer the phone.
Four loans, three lenders, zero clear picture?
Plenty of investors do not have one loan. They have an owner occupier loan with one bank, an investment loan with another, maybe a line of credit somewhere else, each with a different rate, different repayment date and different balance. Adding that up by hand after every rate change is a chore, and a chore that gets skipped is a blind spot.
This is also why property tracking becomes increasingly useful when you are considering refinancing or another property purchase.
Open Banking: one view across your loans
This is where Open Banking earns its keep. With Property Dollar’s premium plan, your live loan balances and rates sync across supported lenders into one view. No logging in to four apps. No guessing which balance is current. Just one clear picture of what you owe, what you are paying and what you have in equity, updated as things change. When the numbers are accurate, every decision after that gets easier.
Loan Buddy: the second opinion that works for you
Seeing your loan clearly is step one. Step two is knowing whether it could be better. Loan Buddy, also in the premium plan, uses your Open Banking data to compare your loan against roughly 4,000 products, looking for potential savings on rate, fixed versus variable options and offset arrangements. It does not push a particular lender at you. If it finds something worth a conversation, you choose whether to speak to a partner broker, and if you do not, nothing happens.
Think of it as a standing check up. Not once when you panic after a rate rise, but continuously, so if your loan stops being optimised you hear about it.
The same principle applies to borrowing power: current property values, debt and equity matter when assessing what you may be able to do next.
It’s not just the rate: how your loan is built can matter just as much
When rates move, almost everyone asks the same question: is my rate competitive? It is a fair question, but it is only part of the answer. Two borrowers on the identical rate can end up paying very different amounts over the years, because what a loan costs also depends on how it is put together.
Take offset accounts. Whether you have one, how it is linked and whether it is actually working as you expect can change the interest you pay. ASIC’s July 2026 review of offset practices at eight major lenders found weaknesses at every bank in how offsets were set up, monitored and managed.
For property investors, offset and redraw can also have very different implications when money is taken back out. Read our guide to offset versus redraw for investment properties.
Then there is the split between fixed and variable, which decides how exposed you are to the next rise. Repayment type matters too, such as interest only versus principal and interest and for how long, as does the loan term. Fees and package costs can quietly eat into a discount, and discounts themselves can lapse. Your LVR matters because lenders often price differently across LVR bands, so a loan that has moved into a better band, or slipped into a worse one, may deserve a fresh look. And if you hold several loans, how they are arranged and secured can affect both flexibility and cost. For investors, structure can also interact with tax outcomes, which is a reason to involve a qualified tax adviser before changing anything.
None of this shows up in a rate comparison table. It is also why the cheapest advertised rate is not always the best outcome, and why sometimes the smartest move is a small structural tweak rather than a full refinance.
This is where an experienced mortgage broker can be very effective. A good broker can see across many lenders, understands how their policies differ, knows which are flexible on the things that matter to your situation, and can weigh trade offs a spreadsheet will not catch. They can also negotiate on your behalf. It is sensible to ask any broker how they are paid and why a particular recommendation suits your circumstances. A good one will welcome the question.
Want a human to run the numbers? It costs nothing.
Some people want software to keep watch. Others want to talk to a person. Property Dollar can connect you with a licensed mortgage broker for a free, no obligation review of your loan. The broker looks at whether your rate is competitive, whether your structure suits your circumstances, and whether refinancing, restructuring, a fixed and variable split or an offset arrangement could bring your costs down. You are not committing to anything by asking.
With repayments stepping up on 9 October, checking now leaves you more options than waiting until a lender raises a concern.
The bottom line: stop paying for what you can’t see
You cannot control the RBA, the banks or the housing cycle. You can control how well you know your own numbers and how quickly you act on them. Four rate rises, six straight monthly price falls and a softening jobs market, with unemployment reaching 4.6% in August, make this a good time to get eyes on your loans. Property Dollar is here to do the watching, the comparing and the flagging, so you can focus on everything else.
FAQ
What is the RBA cash rate now?
The Reserve Bank of Australia increased the cash rate target by 25 basis points to 4.60% at its 29 September 2026 meeting. The new rate became effective from 30 September 2026. It was the fourth cash rate increase during 2026.
How much could the latest rate rise add to my mortgage repayment?
The actual amount depends on your loan balance, rate, repayment type and remaining term. ABC News calculated that a 0.25 point increase adds about $91 per month to repayments on a $600,000 variable loan with 25 years remaining. Across the four increases during 2026, the same example is roughly $360 more per month.
Why should I check my equity and LVR after a rate rise?
A rate rise does not directly change your property value, but higher repayments can affect household cash flow while changing property values can alter your equity and LVR. If your property value falls while your loan balance remains similar, your equity falls and your LVR rises.
How can Property Dollar help me monitor several home loans?
Property Dollar Premium can use Open Banking to bring current loan balances and rates from supported lenders into one view. This can make it easier to see what you owe, what rates apply and how those loans relate to your property values, equity and LVR.
What is Loan Buddy?
Loan Buddy is a Property Dollar Premium feature that uses Open Banking information to compare your existing loan against roughly 4,000 loan products. It can identify potential differences involving rates, fixed versus variable options and offset arrangements. If something looks worth investigating, you can choose whether to speak with a partner mortgage broker.
Does a lower advertised interest rate always mean a better home loan?
No. The overall outcome can also depend on offset arrangements, repayment type, loan term, fees, discounts, LVR and how different loans are structured.
Should I refinance because the RBA has increased rates?
Not necessarily. A review may find that refinancing is worth considering, but it could also identify another option such as negotiating with your current lender, changing the loan structure, reviewing an offset arrangement or making no change. Property Dollar can connect users with a licensed mortgage broker for a free, no obligation review, but Property Dollar itself does not provide credit advice.
Can Property Dollar tell me whether I should refinance my home loan?
No. Property Dollar does not provide credit advice or tell you whether you should refinance. It can help you monitor your property value, loan balance, equity, LVR and other loan information, while Loan Buddy can identify potentially relevant loan alternatives for comparison. Any recommendation to refinance, restructure or change your loan should come from an appropriately licensed mortgage professional who considers your individual circumstances.
Sources
- Reserve Bank of Australia, Statement by the Monetary Policy Board, 29 September 2026
- ABC News, Major banks raise interest rates after RBA cash rate decision, 30 September 2026
- ABC News, The RBA just raised rates. It affects more than your home loan, 29 September 2026
- ASIC, hidden mortgage offset failures, July 2026
- Cotality Home Value Index, September 2026, via PropertyUpdate, 1 October 2026
- Australian Bureau of Statistics, Labour Force, August 2026
- APRA June quarter 2026 property exposures, as reported by Canstar
The LVR example is illustrative and was calculated by Property Dollar. Loan Buddy and Open Banking features are part of Property Dollar Premium, and savings are not guaranteed.