What Is Debt to Income Ratio? The 6 Times DTI Rule Property Investors Need to Understand
- September 30, 2026
You own property.
Your equity has grown.
Your LVR looks reasonable.
You have a deposit available for another investment.
So you assume the bank should be comfortable lending you more.
Then your broker mentions three letters:
DTI.
For Australian property investors, understanding debt to income ratio is becoming increasingly important because a strong equity position does not automatically mean strong borrowing capacity.
You can have hundreds of thousands of dollars in property equity and still encounter borrowing constraints.
Here is why.
What is debt to income ratio?
Debt to income ratio, commonly called DTI, compares the amount of debt a borrower has with their income.
At a simple conceptual level:
DTI = total debt divided by annual gross income
For example, imagine an investor has:
Total relevant debt of $900,000
Annual gross income of $150,000
Their simple DTI would be:
$900,000 divided by $150,000 = 6
That means their debt is approximately six times their annual gross income.
Actual lender and regulatory calculations can involve specific definitions and treatments of debts and income, so this simple calculation should be viewed as an illustration rather than a lender assessment.
Why is six times DTI important in Australia?
The number six has become particularly important because of APRA’s macroprudential settings.
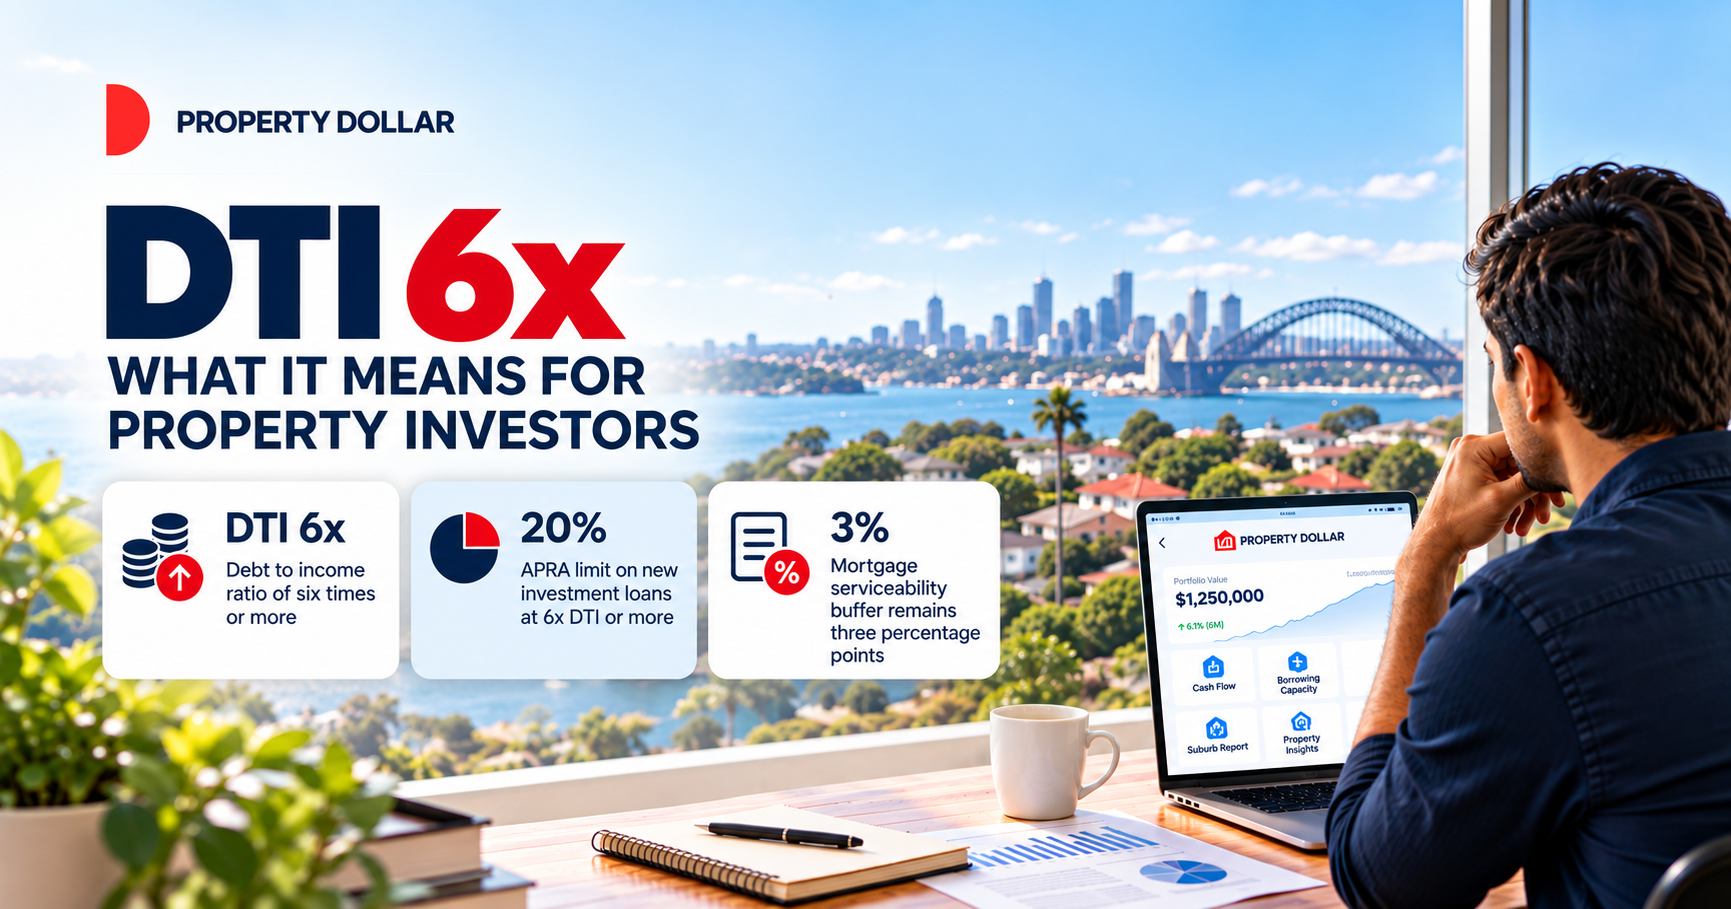
From 1 February 2026, APRA introduced limits on the proportion of new residential mortgage lending that banks can fund at a DTI of six times or more.
APRA allows authorised deposit taking institutions to fund up to 20 per cent of new investment loans at a DTI of six times or more.
A separate 20 per cent limit applies to new owner occupied loans at the same DTI threshold.
There is an important distinction here.
A DTI of six is not an automatic borrowing ban.
APRA has placed a limit on the proportion of high DTI lending a regulated lender can fund.
That means individual lending decisions still depend on the lender, the borrower’s circumstances, serviceability, credit policy and other factors.
Why did APRA introduce the DTI limits?
APRA identified high household indebtedness as an important vulnerability in Australia’s financial system.
When announcing the measure, APRA said housing credit growth had increased and high DTI borrowing had begun to rise from relatively low levels, driven particularly by investor borrowing activity.
The policy is designed to contain a potential build up of housing related financial vulnerabilities rather than prevent Australians from investing in property.
The latest numbers are worth watching.
APRA’s June 2026 property exposure statistics show that investment lending represented 35.6 per cent of new residential loans funded during the quarter.
Among new investment loans, 8.9 per cent had a DTI of six times or more, compared with 8.7 per cent a year earlier.
That remains well below APRA’s 20 per cent portfolio limit, but it demonstrates why DTI is now an important number for investors to understand.
DTI and LVR measure different things
This is where investors can easily become confused.
LVR asks:
How large is the loan compared with the property’s value?
DTI asks:
How large is the borrower’s debt compared with their income?
They measure different risks.
Consider an investor with a property portfolio worth $1.5 million and total property debt of $900,000.
Their portfolio LVR would be approximately 60 per cent.
On the surface, that may appear to represent a substantial equity position.
But suppose their annual gross income is $150,000.
Their simple DTI would be approximately six.
The investor therefore has:
Property value: $1,500,000
Debt: $900,000
Equity: $600,000
LVR: 60 per cent
Illustrative DTI: 6
This is a powerful example of why equity and borrowing capacity are not the same thing.
If you want to understand the LVR side of the equation in more detail, read Can You Answer What’s My LVR Without Calling Your Bank?, which explains why monitoring LVR can become increasingly important as property values and loan balances change.
An investor can have significant equity but still face borrowing constraints because lenders must also consider income, expenses, existing commitments and serviceability.
Your property can become more valuable without your borrowing position improving equally
Imagine your $1.5 million portfolio grows to $1.65 million.
Assuming debt remains at $900,000, your equity increases from $600,000 to $750,000.
Your LVR improves.
But if your income remains $150,000 and relevant debt remains $900,000, your simple DTI remains approximately six.
So you can become substantially wealthier on paper without receiving a corresponding increase in borrowing capacity.
This is why understanding your broader borrowing position matters alongside tracking equity. In What If You Knew Your Exact Borrowing Power at All Times?, we explore the factors that can influence how much you may be able to borrow as your portfolio changes.
This is one of the most important distinctions for investors planning their next purchase.
Equity answers whether you have wealth tied up in property.
Serviceability and lending criteria help determine whether a lender may allow you to borrow more.
DTI is not the same as serviceability
Another common mistake is treating DTI and serviceability as interchangeable.
They are not.
DTI compares debt with income.
Serviceability is a broader lender assessment of whether the borrower appears able to meet repayments.
That assessment can consider income, living expenses, existing loan commitments, credit limits, dependants, loan terms, interest rates and lender policy.
APRA has also maintained its mortgage serviceability buffer at three percentage points.
So an investor may need to navigate several different lending measures simultaneously.
That is why asking only:
How much equity do I have?
does not provide the complete answer.
Borrowing capacity is only part of the equation. Investors also need to understand what changing repayments could mean for the property’s ongoing finances. Our guide How to Stress Test Your Investment Property Cash Flow When Interest Rates Change shows how different rate scenarios can affect portfolio cash flow.
What debts can affect DTI?
The regulatory calculation is more detailed than simply adding up property mortgages.
Depending on the applicable definitions and lender treatment, relevant debt can extend beyond the loan against the property you are considering.
This is another reason investors should not treat an online DTI calculation as a formal credit assessment.
The useful purpose of an indicative DTI calculation is different.
It helps you understand the relationship between your overall debt and income before you start making assumptions about another purchase.
For an actual lending decision, your mortgage broker or lender should calculate your position using the relevant lending criteria.
Why portfolio investors should pay particular attention
DTI becomes increasingly relevant as a portfolio grows.
Your first property might involve one mortgage.
Your second introduces another.
Your third may arrive after you have extracted equity from an earlier property.
Over time, you can accumulate:
Property loans
Owner occupied debt
Investment debt
Other financial commitments
At the same time, your properties may be appreciating and your equity may be increasing.
That can create an interesting situation:
Your net property equity may be improving while your borrowing flexibility becomes tighter.
This is why portfolio investors need visibility over both sides of their position.
Keeping those numbers together can also make refinancing and future purchase conversations easier to prepare for. How Do Property Tracking Apps Help Plan Refinancing and New Purchases? explains how portfolio visibility can support that planning process.
Not simply what they own.
But what they owe.
Why falling property values add another dimension
In our previous article, Property Values Are Falling: What Happens to Your Equity and LVR?, we explained how a decline in property value can reduce equity and increase LVR even when the loan balance has not changed.
DTI adds another layer.
Property values influence your equity and LVR.
Income and debt influence your DTI.
Interest rates and expenses influence serviceability and cash flow.
These numbers interact, but they are not interchangeable.
An investor looking at only one of them may be missing an important part of the portfolio.
Current lending conditions make this worth understanding
Australian housing lending has recently slowed.
ABS reported that the number of new home loans fell 5.4 per cent in the June quarter of 2026.
Investor lending experienced an even larger decline, with the number of new investor loans falling 8.6 per cent during the quarter.
NSW investor loan numbers fell 15.5 per cent, Victoria fell 14.2 per cent and Queensland fell 10.1 per cent.
Australian Bureau of Statistics
At the same time, the RBA cash rate currently stands at 4.35 per cent, effective from 12 August 2026. The next monetary policy decision is due on 29 September 2026, so this figure should be checked again if the article is published after that announcement.
The lesson is not that investors should stop borrowing.
It is that investors need a clearer understanding of their complete position before assuming their next purchase is financially achievable.
Five numbers property investors should know
Instead of asking only what your property is worth, consider these five numbers together.
Property value
What are your properties currently estimated to be worth?
Outstanding debt
How much do you currently owe?
Equity
What is the difference between estimated property value and outstanding property debt?
LVR
What proportion of the property’s estimated value is represented by the loan?
DTI
How does your relevant debt compare with your annual income?
None of these numbers provides the complete picture by itself.
Together, they can help you ask much better questions.
Where Property Dollar fits
Property Dollar is designed to help property owners see more of their portfolio in one place.
You can track property values, loans, equity, LVR, expenses and cash flow rather than relying on disconnected spreadsheets, property portals and bank accounts.
That visibility does not replace a lender, mortgage broker, accountant or financial adviser.
It helps you understand your portfolio before those conversations happen.
Because the question for an investor is rarely just:
How much is my property worth?
It is increasingly:
What do my property value, equity, debt, LVR, income and cash flow collectively say about my position?
And as Australian lending rules evolve, understanding those relationships becomes even more valuable.
Know your portfolio before planning the next property
A large amount of equity can be valuable.
But equity alone does not determine whether you can finance another purchase.
DTI, serviceability, income, expenses, lender policy and lending limits can all matter.
The more properties you accumulate, the more important it becomes to understand the entire picture.
Know what you own.
Know what you owe.
Know the numbers before you plan the next move.
This article contains general information only and does not constitute financial, credit, tax or investment advice. Lending criteria vary between lenders and individual circumstances. Consider seeking advice from appropriately qualified professionals before making borrowing or investment decisions.
FAQ
What is a DTI ratio in Australia?
DTI compares a borrower's relevant debt with their annual income. A simple illustrative calculation divides total debt by annual gross income. Lenders and regulatory reporting use specific definitions, so an indicative calculation may differ from a formal lending assessment.
What does a DTI of six mean?
At a simple level, a DTI of six means debt is approximately six times annual income. For example, $900,000 of debt compared with $150,000 of annual gross income produces an illustrative DTI of six.
Does APRA ban loans above six times income?
No. APRA's policy limits regulated lenders to funding up to 20 per cent of new investment loans at a DTI of six times or more, with a separate 20 per cent limit for owner occupied lending. It is not a universal prohibition on an individual borrowing above six times income.
Is DTI the same as LVR?
No. LVR compares a loan with a property's value. DTI compares debt with income. An investor can therefore have a relatively low LVR while still having a relatively high DTI.
Can I have lots of equity but limited borrowing capacity?
Yes. Property equity is only one part of a lending assessment. Income, existing debts, expenses, serviceability, lender policy and regulatory lending settings can also influence borrowing capacity.
What is APRA's current mortgage serviceability buffer?
APRA confirmed in May 2026 that the mortgage serviceability buffer remains at three percentage points.
Does DTI include investment property debt?
Investment property borrowing can contribute to the debt used in DTI assessments. Exact calculations depend on regulatory definitions and lender treatment.
How can property investors monitor their financial position?
Investors can monitor estimated property values, outstanding loans, equity, LVR, rental income, expenses and cash flow together. DTI and formal borrowing capacity should be confirmed with the relevant lender or mortgage professional.