One Unchecked Loan Gap Can Cost More Than a Rate Rise
- October 14, 2026
Open Banking is about to make more of the lending market visible
Australians refinanced $67.1 billion of home loans to a different lender in the June quarter of 2026.
That included $41.9 billion of owner occupier loans and $25.2 billion of investor loans, according to the Australian Bureau of Statistics.
Australian Bureau of Statistics
Refinancing is not a niche activity.
A large number of Australians are actively checking whether their existing mortgage still stacks up against the market.
Others may not have looked closely at their loan since settlement.
And with the RBA cash rate now sitting at 4.60%, that difference matters more. The Reserve Bank increased the cash rate by another 25 basis points on 29 September, taking it to its highest level in many years.
The question is no longer simply:
What rate am I paying?
It is:
How far is my current loan from what may be available elsewhere?
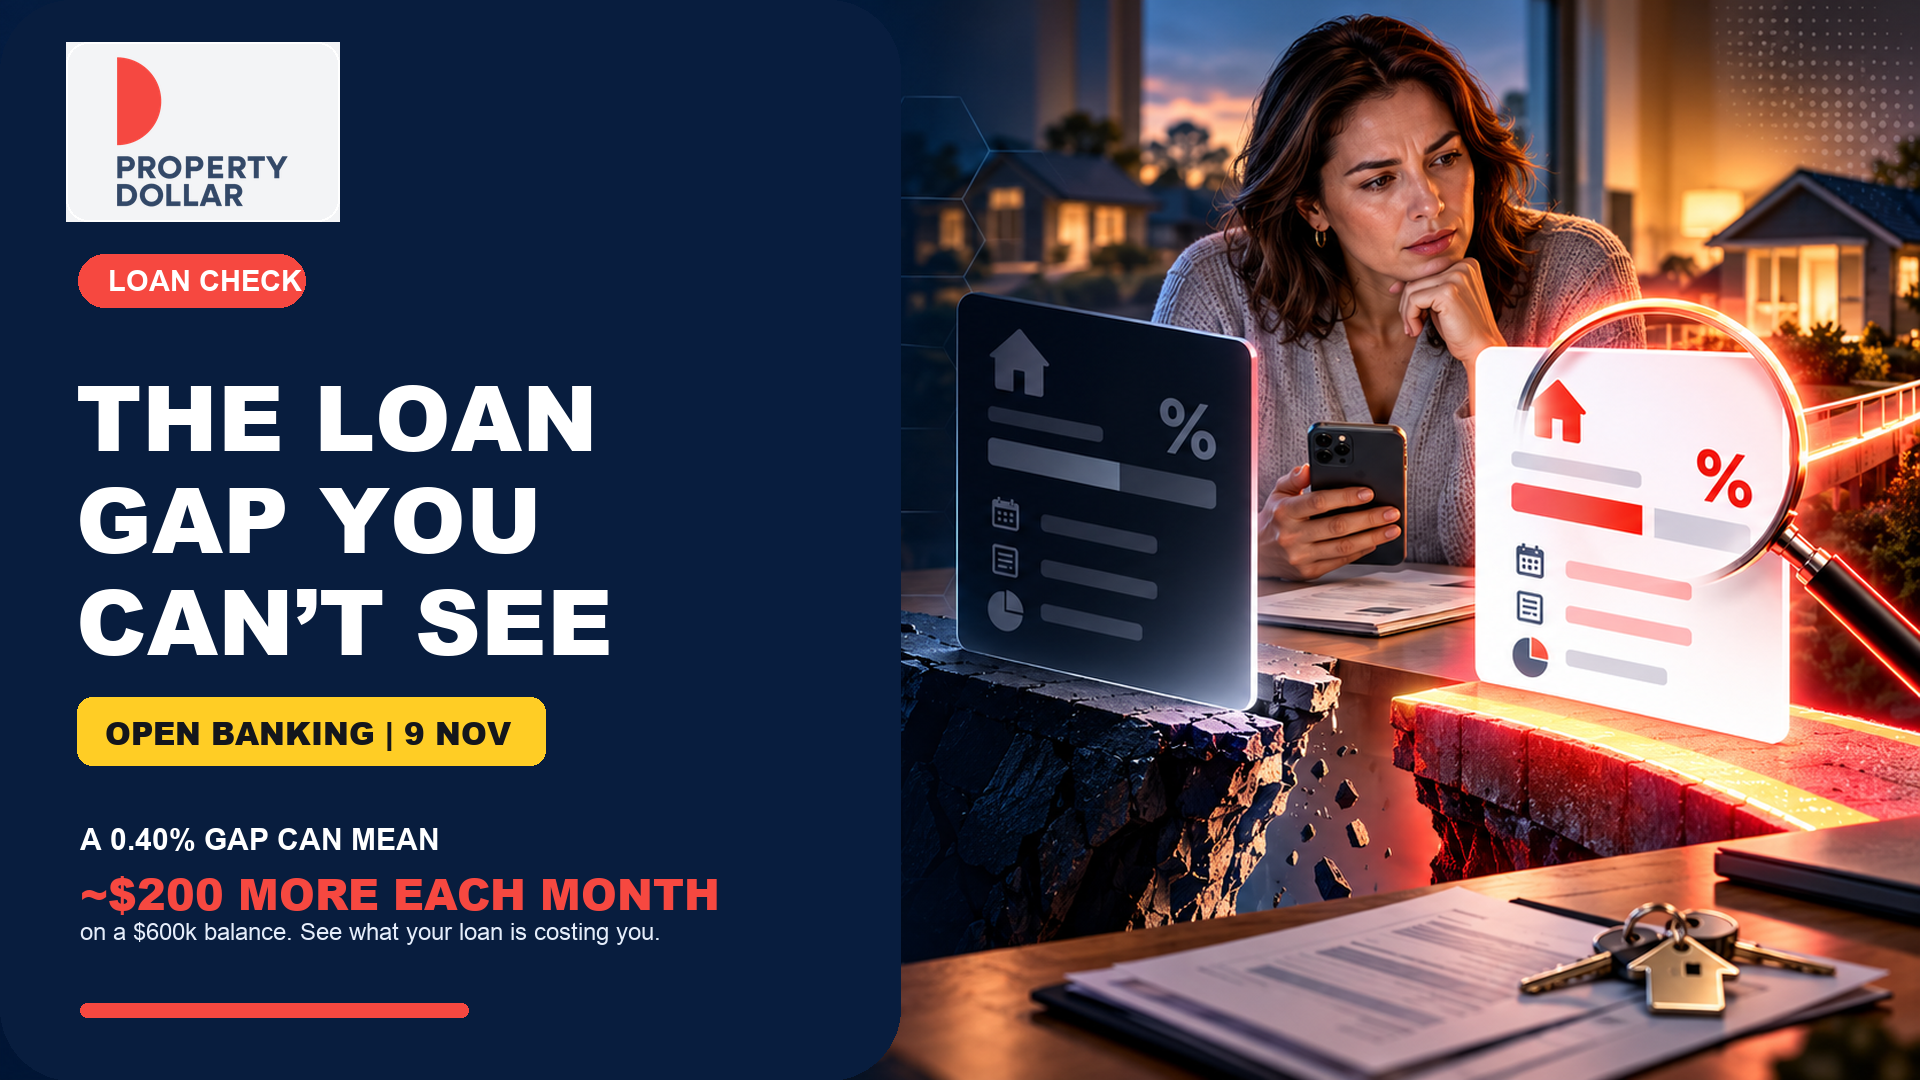
And from 9 November 2026, Open Banking starts expanding further into the non bank lending market, making that question easier for more borrowers to investigate.
The $200 a month question
Start with the maths.
Imagine you have a $600,000 mortgage.
If your interest rate is around 0.40 percentage points higher than another suitable loan available to you, that difference represents roughly:
$2,400 in additional interest during the first year
or approximately:
$200 per month
That is a simplified example and does not include fees, loan structure, changing balances or other lending considerations.
But it demonstrates why relatively small differences in mortgage rates can matter.
For comparison, the latest 0.25 percentage point RBA increase has been estimated to add roughly $91 a month to repayments for a borrower with a $600,000 variable loan and 25 years remaining. CDR-Open-Banking-Non-Bank-Lende…
So an unchecked loan gap of 0.40 percentage points can potentially cost more each month than an individual 0.25 percentage point RBA increase.
The difference is that the RBA sets the cash rate.
Your loan gap is specific to your mortgage.
Do older borrowers always pay more?
Not necessarily.
The size of the gap between existing and new mortgage rates changes over time.
Previous RBA research found periods where longer standing variable loans were paying materially higher rates than newer borrowers.
Later RBA research showed that difference can narrow when lenders become more aggressive about retaining existing customers. CDR-Open-Banking-Non-Bank-Lende…
That is why broad claims about a permanent mortgage loyalty penalty can be misleading.
There is only one reliable way to know whether your loan has fallen behind:
Compare your actual loan against current alternatives.
Falling property values can also shrink your options
Interest rates are only one side of the equation.
Your property value affects your loan to value ratio, which can influence refinancing options and lender pricing.
Cotality’s September Home Value Index showed national housing values fell 1.1% during September.
That was the sixth consecutive monthly decline and left national values approximately 5.2% below their March 2026 peak.
Consider a property worth:
$800,000
with an outstanding mortgage of:
$640,000
That represents an LVR of:
80%
Now suppose the property’s value falls 5% to:
$760,000
while the mortgage remains $640,000.
The new LVR becomes approximately:
84.2%
Nothing changed with the loan.
No repayment was missed.
No additional money was borrowed.
But the borrower’s lending position changed because the property value moved.
This is why the opportunity to refinance is not necessarily static.
Knowing your current property value, current loan balance, equity and LVR can help you understand whether the window available to you is changing.
9 November: the non bank Open Banking gap starts to close
Open Banking forms part of Australia’s Consumer Data Right.
Consumer data sharing began with banking in 2020 and has progressively expanded.
For non bank lenders, product data sharing obligations started on 13 July 2026.
Consumer data sharing begins in stages from 9 November 2026, depending on the size and implementation timetable of the provider. Larger providers have later commencement requirements.
The ACCC says at least 35 new data holders will enter the Consumer Data Right through the non bank lending expansion.
It also reports that more than 1.3 million Australians are already using the Consumer Data Right, an increase of approximately 135% over the previous year.
This matters because non bank lenders account for mortgages, personal loans, vehicle finance and other significant household debts.
As individual lenders become available, borrowers may increasingly be able to authorise accredited services to access their loan information in the same secure framework already used across participating banks.
It will not happen everywhere on one day.
Coverage will expand progressively.
But the direction is important.
More of a borrower’s lending position can potentially become visible in one place.
Why this matters for property investors
Property investors frequently have more complicated lending arrangements than a single home owner mortgage.
You may have:
A home loan with one lender
An investment loan with another
Another investment property financed elsewhere
Different interest rates
Different repayment structures
Different loan balances
Different LVR positions
The difficulty is not necessarily understanding each number individually.
It is keeping all those numbers current at the same time.
That is where Open Banking becomes useful.
From scattered lender portals to one view
Property Dollar Premium can connect supported loan accounts through Open Banking.
Instead of manually checking several lender portals, investors can bring information such as current loan balances and interest rates into their Property Dollar portfolio view.
Those loan figures can then sit alongside property values, equity and LVR.
The objective is simple:
Know what you own.
Know what you owe.
Know how the relationship between the two is changing.
Property Dollar already uses Open Banking to help investors maintain a clearer view of their loans and equity rather than relying entirely on manually updated spreadsheets.
Seeing the loan is step one. Comparing it is step two.
Visibility tells you where you stand.
The next question is whether your current mortgage still compares favourably with alternatives.
That is where Loan Buddy comes in.
Loan Buddy is available within Property Dollar Premium and can compare a connected loan against roughly 4,000 loan products.
It considers factors such as:
Current interest rate
Loan amount
LVR
Fixed versus variable structures
Offset options
Potential savings thresholds
The objective is not to tell you that you must refinance.
It is to surface situations where the difference may be large enough to justify a closer look. Property Dollar’s existing guidance describes Loan Buddy as a tool that identifies when current loan conditions suggest it may be worth investigating alternatives.
A lower rate can do more than reduce next month’s repayment
The benefit of a better loan is not necessarily limited to immediate cash flow.
Consider a simplified example.
A borrower has:
$600,000 outstanding
25 years remaining
6.50% interest
Suppose an alternative loan was available at 6.10% and the borrower continued making approximately the same repayment rather than reducing it.
Under those assumptions, the lower rate could potentially shorten the loan term considerably and reduce lifetime interest.
The original analysis calculated a potential reduction of roughly two years and around $98,000 in lifetime interest, assuming rates remained unchanged. CDR-Open-Banking-Non-Bank-Lende…
Real outcomes will differ because rates move, loan balances decline, fees apply and individual products have different terms.
But the example demonstrates a broader point:
The value of comparing mortgages is not necessarily confined to this month’s repayment.
The lowest headline rate is not always the best loan
A comparison should go beyond the advertised percentage.
The right questions can include:
Is the loan variable or fixed?
Does it include an offset account?
What fees apply?
Are there break costs?
What happens to repayments?
How does the new loan term compare?
Does your current LVR qualify?
Would refinancing restart a longer loan term?
Are there tax implications for an investment property?
Does the structure still suit what you are trying to achieve?
A cheaper advertised rate can still produce an inferior outcome if the broader structure does not suit the borrower.
This is why any actual refinancing decision needs to consider the complete lending position.
Prefer to talk it through?
Software can identify a potential opportunity.
A licensed mortgage broker can assess whether pursuing it actually makes sense.
Property Dollar works with partner mortgage brokers who can review issues including:
Your current rate
Available alternatives
LVR
Fixed rate break costs
Discharge and application fees
Loan structure
Lender eligibility
Timing
The review is free and carries no obligation to proceed.
Property Dollar itself does not provide credit advice.
Any recommendation to refinance or change a loan must come from an appropriately licensed mortgage professional who considers your individual circumstances. CDR-Open-Banking-Non-Bank-Lende…
See if your loan could be working harder for you.
Connect your loans with Property Dollar Premium to see your balances, rates, equity and LVR in one place.
Loan Buddy can help identify whether there may be a meaningful gap between your existing loan and current alternatives.
And if you want someone to examine the numbers with you:
Book a free loan review with a licensed partner mortgage broker.
The rate you cannot control, and the gap you can check
Four RBA rate increases during 2026 have understandably focused borrowers on the cash rate.
The current cash rate is 4.60%.
You cannot change that.
But you can investigate the relationship between:
The rate you currently pay
and
What may be available to a borrower in your circumstances today.
At the same time, falling property values can alter equity and LVR, potentially changing the refinancing options available.
And from 9 November, the Consumer Data Right begins extending consumer data sharing into the non bank lending sector, gradually bringing more loans into the Open Banking ecosystem.
Checking your mortgage is not about assuming there is always a better deal.
It is about knowing.
Because the cost of a loan gap is straightforward to calculate.
You simply need to find the gap first.
FAQ
What changes on 9 November 2026 for Open Banking?
Consumer data sharing begins progressively for eligible non bank lenders from 9 November 2026. This allows customers of participating lenders to authorise accredited services to access eligible loan information through Australia's Consumer Data Right framework. Coverage will expand progressively rather than all non bank lenders becoming available simultaneously.
Does Open Banking mean Property Dollar can see my loan without permission?
No. Consumer Data Right sharing is permission based. The customer chooses whether to authorise an accredited service to access eligible financial information.
How much could a 0.40% mortgage rate difference cost?
As a simplified illustration, a 0.40 percentage point difference on a $600,000 balance represents approximately $2,400 of additional interest during the first year, or around $200 per month. Actual results depend on the loan balance, rate, repayment structure and other factors.
What does falling property value have to do with refinancing?
A lower property value can increase your LVR even when your loan balance does not increase. Higher LVRs may affect which lenders or products are available and the pricing offered.
What is Loan Buddy?
Loan Buddy is a Property Dollar Premium feature that compares connected mortgage information against roughly 4,000 loan products. It helps identify situations where current market alternatives may warrant further investigation.
Does Property Dollar recommend which lender I should refinance to?
No. Property Dollar does not provide credit advice. Loan Buddy can help surface potential comparison opportunities, while an appropriately licensed mortgage professional should assess whether refinancing or changing loan structure is suitable for your circumstances.
Is refinancing always worthwhile when another lender offers a lower rate?
No. Interest rate is only one consideration. Fees, break costs, loan term, features, LVR, repayment structure and individual eligibility can all affect whether changing loans produces a better overall result.